The offer on the Gulf-front condo was accepted. The inspection came back clean. Then the buyer's lender called with news that had nothing to do with credit score or income: the building didn't qualify for a conventional loan, and the buyer would need thirty percent down instead of the ten percent they'd budgeted for. That single phone call added roughly $140,000 in cash they hadn't planned to bring to closing on a $700,000 unit.
That scenario plays out often enough along Perdido Beach Boulevard that it deserves more attention than it gets. Most comparisons of Orange Beach condos and houses stop at the list price. The number that actually separates the two isn't on the listing sheet. It's in the mortgage application.
Two Kinds of Mortgages for One Zip Code
Most Gulf-front condo towers in Orange Beach carry a classification lenders call "non-warrantable." Fannie Mae and Freddie Mac won't buy the loan on the secondary market when a building allows nightly rentals, runs like a hotel with front-desk check-in, or has a high ratio of investor-owned units to owner-occupied ones. A single owner holding more than ten percent of the units in a building can trigger it too. None of that reflects the quality of the property. It reflects how the building operates.
The practical effect is that buyers of these units typically need a portfolio loan, a jumbo non-QM product, or cash, since a lender who can't resell the loan has to keep the risk in-house. Down payment requirements commonly run twenty to thirty percent, well above the ten percent some conventional condo loans still allow.
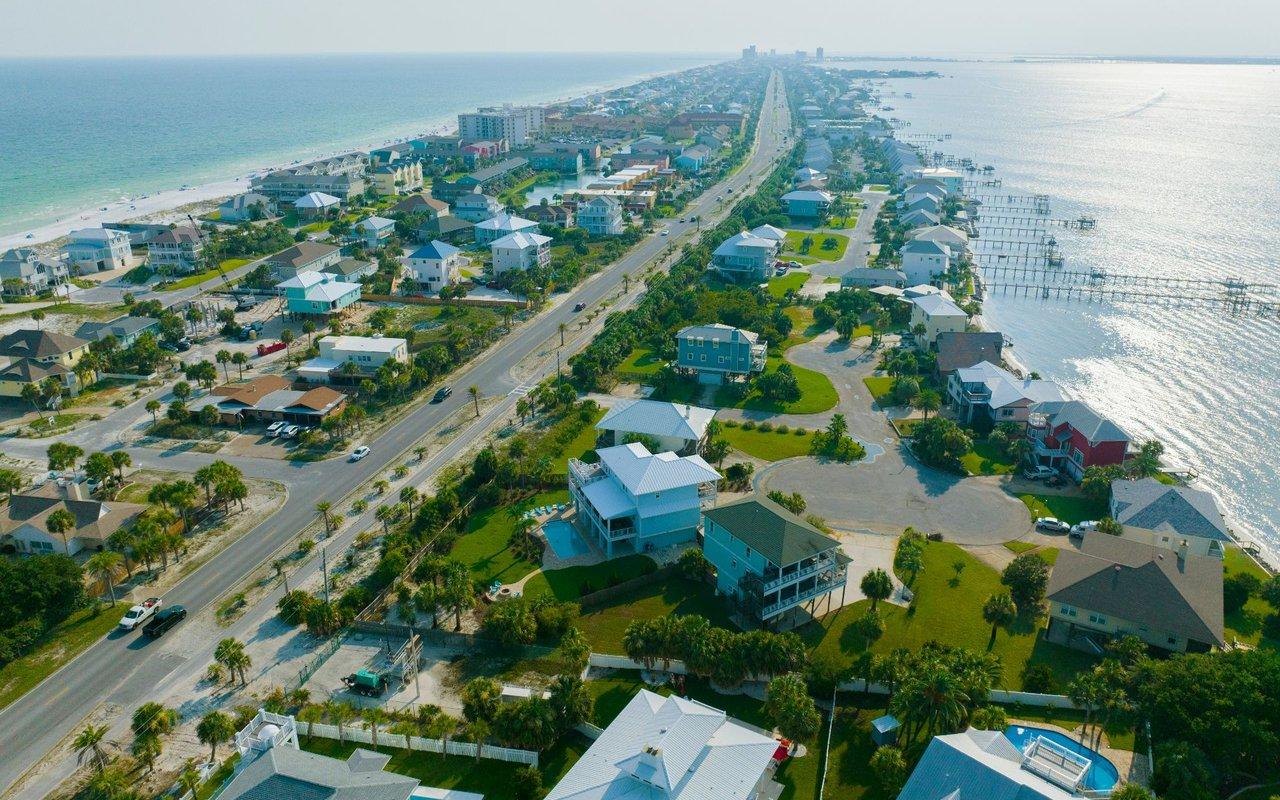
Canal-front and bay-front single-family homes in Orange Beach don't carry that classification at all. A house on Ono Island, Terry Cove, or Cotton Bayou qualifies for standard conventional, jumbo, or VA financing the same way a house anywhere else does. There's no building financial review, no reserve-fund audit, no rental-ratio calculation standing between the buyer and the closing table.
Veterans face an even sharper version of this split. VA loans require the specific condo project to appear on the VA's own approved list, a separate approval process from conventional warrantability. A condo can be warrantable and not VA-approved, VA-approved and not warrantable, both, or neither. A single-family home skips that entire layer of paperwork.
What the Same $700,000 Actually Requires in Cash
Put two Orange Beach properties side by side at the same list price and the financing gap becomes a real number, not an abstraction.
| Gulf-front condo (non-warrantable) | Canal or bay-front house | |
|---|---|---|
| Typical loan type | Portfolio, jumbo non-QM, or cash | Conventional, VA, or standard jumbo |
| Typical down payment | 20% to 30% | As low as 0% (VA-eligible) up to 20% |
| Extra underwriting step | Building reserves, litigation history, rental ratio | Standard appraisal and borrower qualification |
| VA condo-list check required | Yes, project-specific | Not applicable |
On a $700,000 purchase, that gap between a ten percent conventional down payment and a thirty percent portfolio-loan down payment is $140,000 in cash the buyer has to produce before a single HOA due or insurance bill ever comes up. That's the real entry cost difference between the two property types, and it rarely shows up in the marketing.
The Square-Foot Math Nobody's Advertising
Here's where the story gets more interesting than a simple financing footnote. Recent market data shows single-family homes in Orange Beach cost about $33 more per square foot than condos on average, which is exactly what most buyers expect. Condos are supposed to be the cheaper way onto the coast.
But look at which way the prices are moving rather than where they currently sit. Over a recent one-week comparison period, single-family list price per square foot rose 1.93 percent while condo list price per square foot rose 9.38 percent, nearly five times faster. That gap between condos and houses isn't stable. It's closing, and closing quickly.
Combine that with the financing math above and the picture shifts. A condo that looks like the budget-friendly option on a per-square-foot basis today may not hold that position for long, and even where it does, the true cash required to close on it can exceed what a comparably priced house demands. The "cheaper" property and the property that's actually cheaper to buy aren't always the same one.
Where the Houses Actually Sit
Orange Beach's single-family waterfront inventory clusters in a handful of recognizable pockets, each with a different price floor and a different boating profile.
Terry Cove and Cotton Bayou sit closer to the mainland side of the city, favored for protected water and proximity to marinas and restaurants, and they tend to be the more accessible entry points for a canal-front house.
Ono Island, reached by a single gated bridge, is the premium tier. Homes there currently range from roughly 2,000 square feet at $500,000 on the low end up to 6,000-square-foot properties well past $5 million. A recent new-construction canal home on the island closed above $2.5 million with five bedrooms and a private pool. Small, quiet cul-de-sacs like Canal Court, tucked into Ono North Phase One, show up rarely enough that buyers who want that stretch of protected water often have to wait for a listing rather than shop one.
For comparison, the Gulf-front condo towers along the same stretch of coastline include Turquoise Place, whose two towers hold roughly 400 units with three-bedroom floor plans running about 2,300 to 2,400 square feet, and The Oasis at Orange Beach, formerly known as Phoenix West II, a 31-story, 398-unit tower completed in 2013. Caribe's three towers sit at Ono Island's western tip with boat slips along Old River and an on-site restaurant. These buildings deliver resort amenities a canal house never will, but they're also the ones most likely to carry the non-warrantable classification and the higher down payment that comes with it.
Insurance has added its own wrinkle at some of these buildings. Assessments tied to master policy increases have caught buyers and owners off guard at individual towers along the beach, a reminder that the HOA statement attached to a listing is a snapshot, not a guarantee of what next year's dues will look like.
Reading the 2026 Market Correctly
Over the three months ending in May 2026, Orange Beach's median home price stood near $690,000, up 6.1 percent from the same period a year earlier. Homes are taking longer to sell than they were, averaging around 101 days on market compared to roughly 76 days the year before, and condo inventory has climbed after several years of scarcity.
That combination changes the calculus for both buyers and sellers. Buyers have more room to negotiate and more time to run the financing math above before committing to a property type. Sellers, particularly of non-warrantable condo units, benefit from pricing that reflects the smaller pool of financeable buyers, since a unit that only cash buyers or portfolio-loan borrowers can purchase draws from a narrower audience than a comparably priced house.
None of this changes what makes Orange Beach worth buying into. Deep-water boating access, Gulf frontage, and a genuine mix of full-time residents and second-home owners have drawn people here for decades. It just means the smartest move a buyer can make before writing an offer is asking the warrantability question before falling in love with the view.
Frequently Asked Questions
Are all Orange Beach condos non-warrantable? No. Warrantability depends on specific building factors like owner-occupancy ratio, developer control, pending litigation, and short-term rental policy. Some towers qualify for conventional financing while others down the street don't. Ask before you write an offer, not after.
Does a lower HOA fee automatically mean a better deal? Not necessarily. A building with fewer amenities may charge less month to month while a resort-style tower with more staffing and broader insurance coverage charges more. The dues figure alone doesn't capture the full cost of ownership.
Can a veteran use a VA loan on a Gulf-front condo? Only if that specific project appears on the VA's approved condo list, which is separate from conventional warrantability. A condo can pass one test and fail the other, so both need to be checked independently.
Is a canal-front house always the more affordable choice? Not on sticker price alone. Ono Island in particular carries premium pricing at the high end. The affordability advantage shows up more clearly in financing terms and predictable underwriting than in the list price itself.
If you're weighing a Gulf-front condo against a canal or bay-front house in Orange Beach and want the financing question answered before you fall for a view, David Coate and the Coate Connection team can walk through both sides of the math with you. Schedule a Free Consultation to start.